NVDA Earnings: Options Are Pricing a ~$17 Move. Is That Too Much?

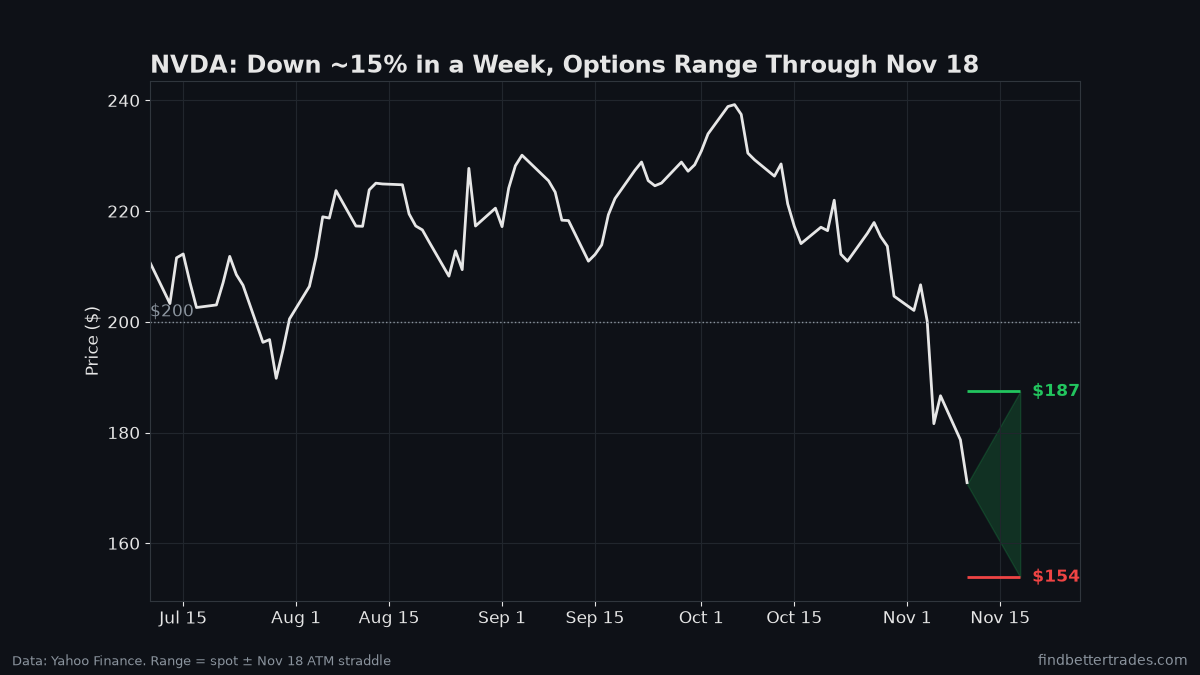
NVDA reports next Tuesday, Nov 17, after the close. And the stock is walking into it bruised. It closed at $200.13 last Wednesday. This morning it’s trading around $170.65. That’s roughly 15% gone in four sessions.
So what’s the options market saying about next week? Pretty loud stuff. Let’s pull the real numbers off the chain and figure out what’s actually priced in, because that’s the part most people skip.
The number: about $17 either way
Here’s the quick-and-dirty way to read an expected move. Take the at-the-money straddle (one call plus one put, same strike) for the first expiration after earnings. That price is roughly what the market thinks the stock can move, up or down, by that date.
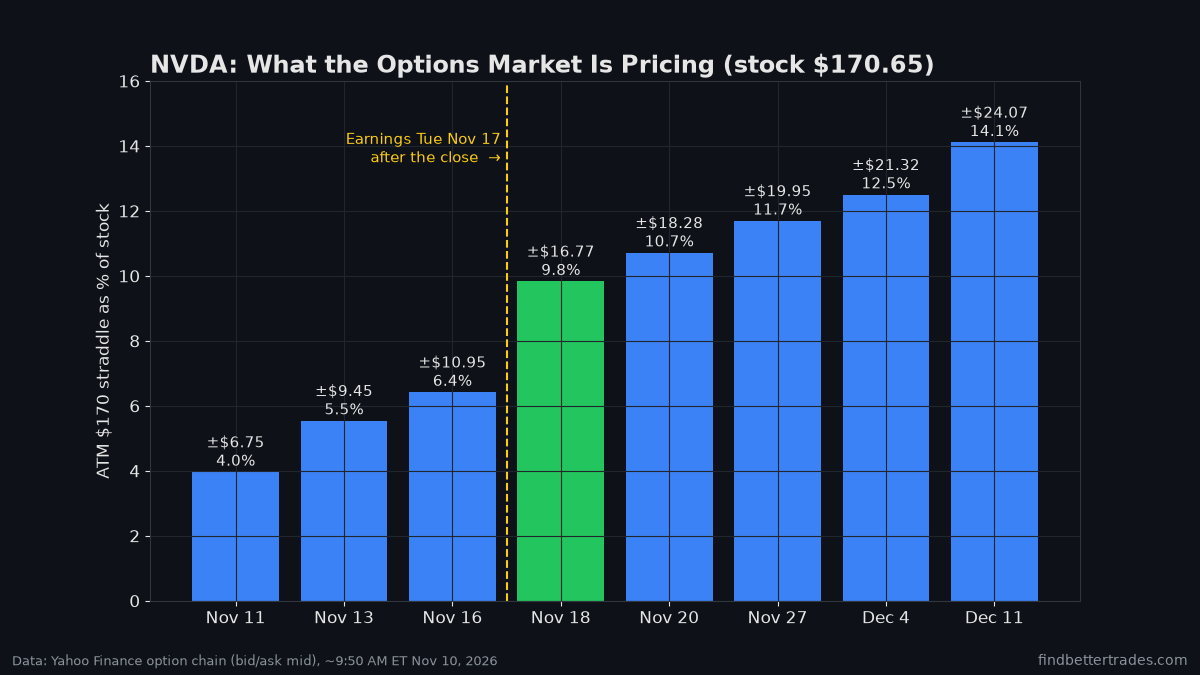
For NVDA, the first expiry after the report is Wednesday, Nov 18. The $170 strike, at bid/ask mid around 9:50 AM ET:
- $170 call: about $9.28
- $170 put: about $7.50
- Straddle: about $16.78, or ±9.8% of the stock
That puts the “priced-in” range through Nov 18 at roughly $154 to $187.
Look at the jump. The Nov 16 straddle (last expiry before earnings) is $10.95. One more expiry, two more days, and it’s $16.78. That gap is the earnings ticket.
Strip out the normal noise
That ~9.8% isn’t all earnings. It also covers six regular trading days, and NVDA’s been moving a lot on regular days lately.
Quick back-of-napkin math. The Nov 16 straddle covers four sessions with no report. Scale that to six sessions, pull it out of the Nov 18 price (in variance terms, which is how vol actually adds up), and what’s left is the earnings piece.
That comes out to about ±$10, or ±5.9%, for the report itself.
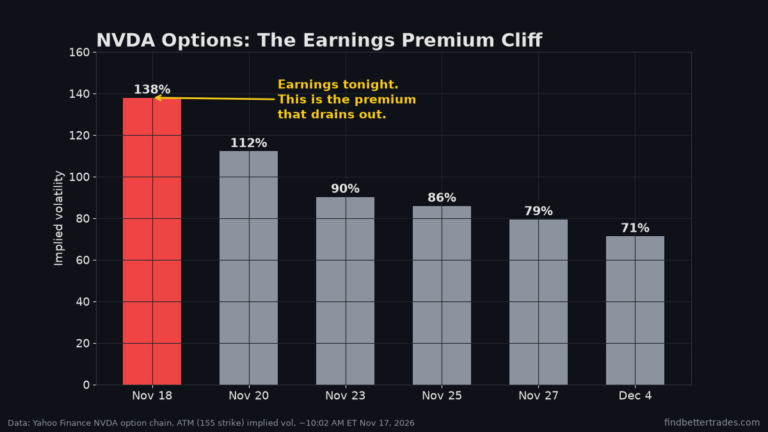
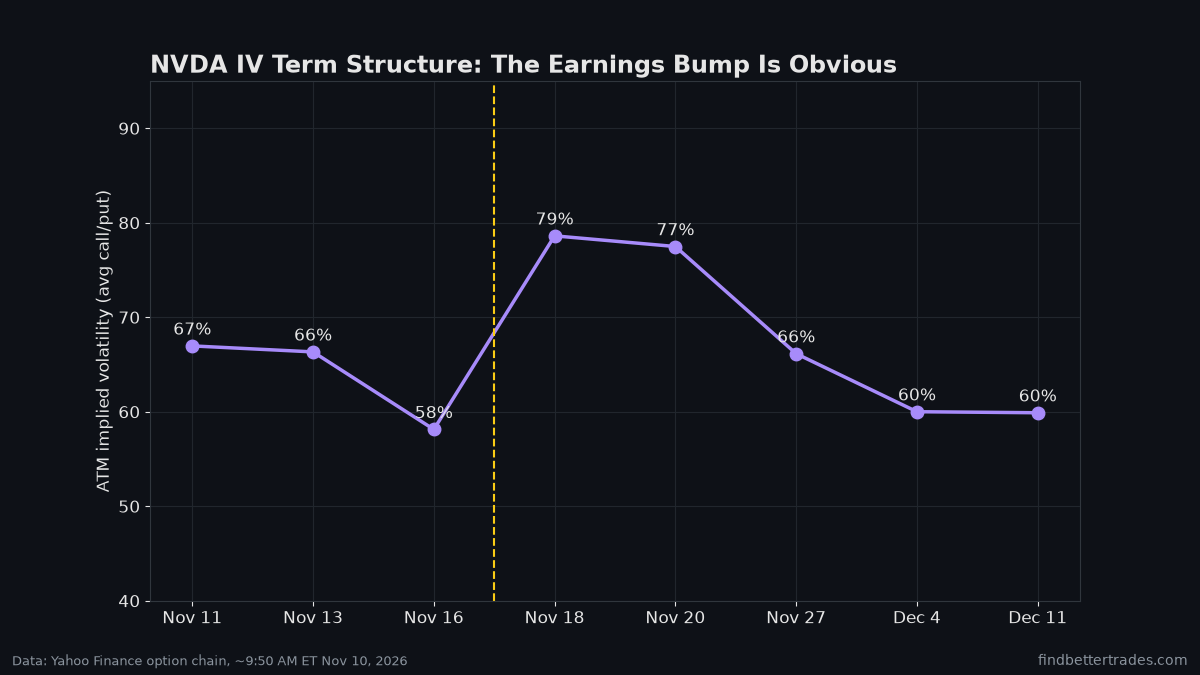
You can see it on the IV curve too. Implied vol sits around 58% on the Nov 16 expiry, then pops to about 79% on Nov 18. That’s the bump. And it gets crushed the morning after the report. Every time.
Is ~6% too much or too little?
Here’s where history helps. I pulled NVDA’s last 16 earnings reactions: close before the report vs. the next day’s close.
- Last 16 reports: average move about 6.7%. Seven of 16 beat 5.9%.
- Last 8 reports: average move about 4.0%. Only 2 of 8 beat 5.9%.
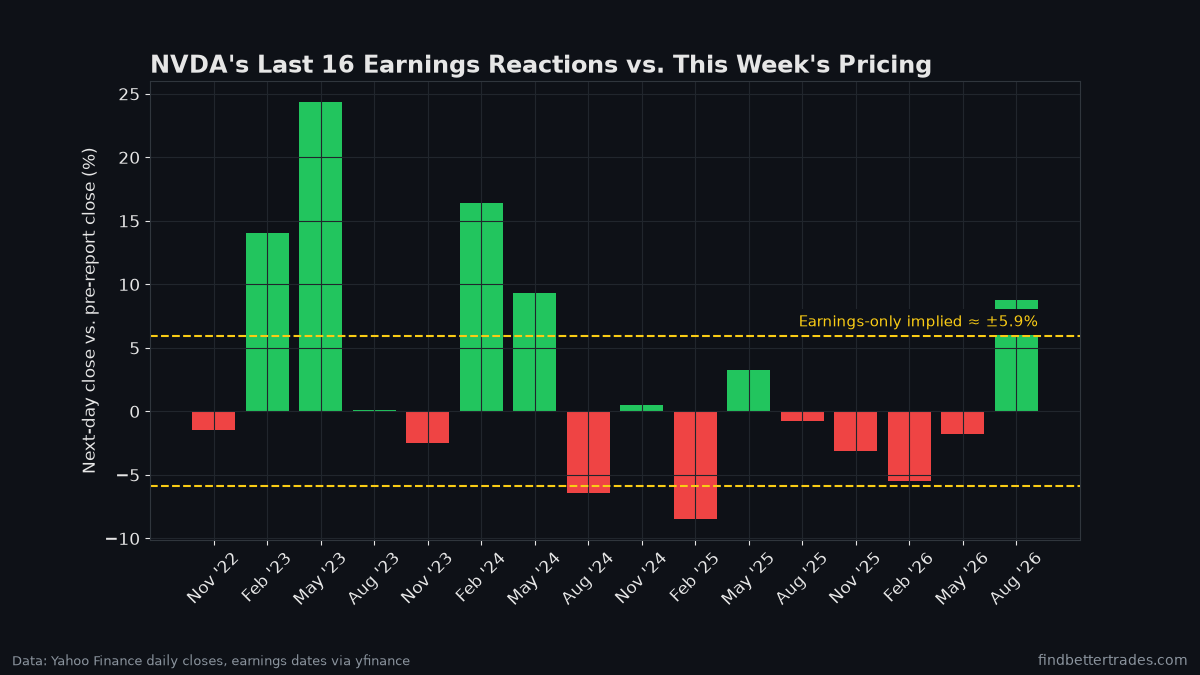
So the old NVDA, the one that ripped 24% and 16% on reports back in 2023 and early 2024, made premium look cheap. The newer, bigger NVDA has mostly moved less than what’s priced. Biggest recent ones: -8.5% in Feb ’25 and +8.7% this August.
That doesn’t mean sell premium and walk away. It means you know what you’re paying for.
The bull case for owning the move
- The stock just dropped about 15% in a week. Sentiment is shaky. Shaky sentiment plus a big number is how you get outsized reactions.
- VIX is back around 21 after spiking to 28 last Thursday. The whole tape is jumpy, not just NVDA.
- When NVDA has gone big, it’s gone really big. A long straddle only needs one of those.
The bear case (for buying premium, anyway)
- You’re paying ~79% IV on the Nov 18 options. That’s going to get cut hard after the print.
- The recent track record says the move usually comes in under what’s priced. Six of the last eight did.
- The stock already moved 15% before the report. Some of the “big move” may have already happened.
How I’d think about it
This isn’t a trade call. It’s a framework.
- Know the range. $154 to $187 through Nov 18 is the market’s line in the sand. Plan around it.
- Long options into earnings? You need the move to beat the straddle, not just “be big.” A 5% pop can still lose money on calls bought at 79% IV.
- Already own shares? The range tells you what the market thinks is a “normal” surprise. If $154 would wreck you, size or hedge before Tuesday, not after.
- Waiting until after? Totally fine. IV crush makes options cheaper the morning after. You give up the gap. You get clarity.
Want a way to play a print without eating the whole IV crush? We broke that down over on TSG: Trading Earnings with Debit Spreads: Beat the IV Crush.
Bottom line
The options market is pricing about a $17 swing through Nov 18, and about $10 of that is the report itself. Recent history says NVDA usually lands inside that. The last week says this one could be different. Either way, you now know the number you’re betting against.
Data: Yahoo Finance via yfinance (NVDA option chain bid/ask mids, daily prices, earnings dates; VIX), pulled ~9:50 AM ET Tue Nov 10, 2026. Prices move fast, so check the live chain. Not financial advice. Options involve risk and aren’t for everyone.
Lesson 68 of 75 in the free Options Trading Course.
← Previous: Options Basics: What That $2 Quote Really Costs
Next: Christmas Tree Spread: Directional Butterfly Strategy →