OTM Options Lottery Tickets: Why Cheap Calls Always Expire Worthless

📊 October 15, 2026
- Out-of-the-money lottery ticket options are mathematically stacked against retail traders, functioning as structural donations to market makers.
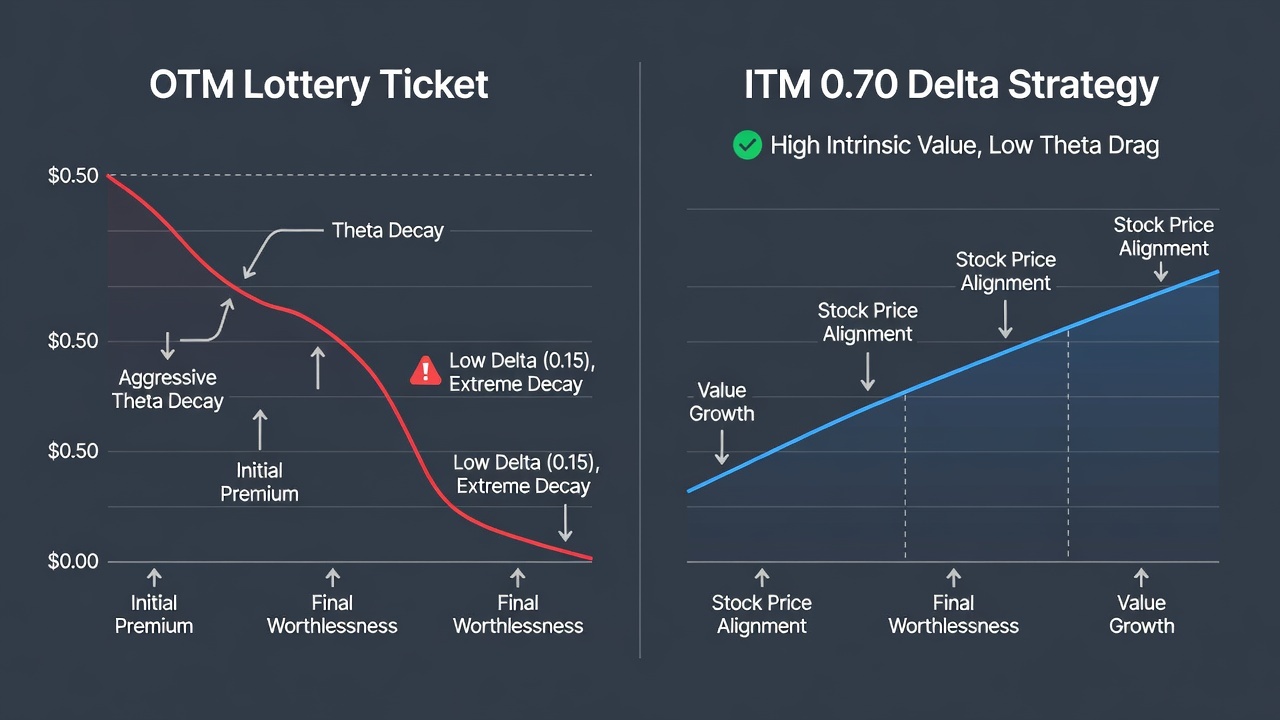
- The fatal flaw is the double-barrel collapse of accelerating theta decay and crushing delta drag, which kills the trade even when your chart direction is right.
- Trade in-the-money contracts with at least a 0.70 Delta or sell out-of-the-money premium via defined-risk credit spreads instead.
— Ben, Find Better Trades
An out-of-the-money option lottery ticket is a far out-of-the-money call or put contract with a low Delta, purchased for pennies in the hope of an outsized windfall. Retail traders flock to them because risking fifty cents per contract feels cheap and harmless. In reality, relentless theta decay and severe probability deficits ensure these positions bleed out and expire worthless the vast majority of the time.
The tool I use for this: Terraline Indicator. Terraline auto-draws algorithmic trendlines that adjust in real time — perfectly connecting the swings you’d spend hours finding manually. Let Terraline Draw For You →
I watch new traders make this exact blunder every single week. They look at a stock trading at $100, see the $120 weekly call priced at $0.25, and convince themselves that turning $250 into $2,500 is just one brisk rally away. That is not trading; that is buying a scratch-off ticket from a broker who is delighted to collect your premium.
Why Everyone Gets This Wrong
Traders mistake low dollar cost for low risk. They look at a $0.30 contract on a $50 stock and conclude that losing thirty dollars is negligible, ignoring that losing 100% of your capital ten times in a row annihilates an account just as fast as one disastrous margin call.
Consider a practical technical setup. Say a stock is consolidating cleanly at $50, riding right along its rising 20-period exponential moving average (EMA) with resistance sitting up at $54. A disciplined trader expects a test of that $54 ceiling over the next two weeks.
Instead of purchasing an at-the-money contract, the lottery buyer scoops up the $58 calls expiring in twelve days for $0.20. When the breakout occurs, the stock rips from $50 to $53.50 over five trading sessions, marking a strong 7% move in the underlying asset.
Yet the lottery ticket still drops in value. Because the stock failed to exceed the strike plus the premium paid, and because time decay accelerates exponentially inside the final fourteen days before expiration, the option loses half its extrinsic value despite a flawless directional chart read. You nailed the technical breakout, yet your brokerage statement shows a 60% loss.
What Actually Works
To profit consistently on directional swings, you must stop buying pure extrinsic hope and start paying for intrinsic value. When I want directional exposure on a clean technical setup, I bypass the bargain bin and target contracts with a Delta of 0.70 or higher.
A 0.70 Delta call behaves like actual stock equity while limiting absolute dollar risk to the premium paid. It carries minimal extrinsic value percentage-wise, meaning daily theta decay will not gut your position while you wait for the chart pattern to resolve.
If capital constraints prevent you from purchasing deep in-the-money contracts, switch to vertical spreads. By buying a slightly in-the-money strike and simultaneously selling an out-of-the-money strike, you finance your trade using the exact lottery-ticket buyers who are throwing their capital away.
| Strategy | Typical Delta | Theta Impact | Real-World Purpose |
|---|---|---|---|
| Far OTM Call | 0.05 – 0.20 | Extreme decay | Gambling on statistical anomalies |
| Deep ITM Call | 0.70 – 0.85 | Low relative decay | High-conviction swing trading |
| Bull Call Debit Spread | Net 0.30 – 0.40 | Decay offset by short leg | Defined-risk tactical breakouts |
Follow a rigid entry rule: only open long directional options when the underlying price holds support above its 20-period EMA, and always choose an expiration cycle at least 45 to 60 days out. This buffer gives your technical idea room to breathe without theta devouring your trade on normal sideways consolidation days.
For exits, cut the position if the underlying asset closes below your primary technical invalidation level, regardless of how much time remains on the contract. Never hold a losing directional option down to zero hoping for a miraculous last-minute recovery.
Free For Traders
One Clear Arrow. Every High-Probability Setup. Free.
The Fusion Indicator combines multiple signals into a single buy/sell arrow on TradingView so you never miss a move.

When Out-of-the-Money Options Can Still Make Sense
Far out-of-the-money options have exactly one legitimate utility: catastrophic portfolio tail-risk hedging. Institutional funds use cheap OTM index puts as disaster insurance against unexpected market shocks, fully intending to write that premium off as an operational expense.
If you choose to use OTM contracts for explosive catalyst trading, keep the allocation capped below 1% of your total account value and treat that capital as already lost. Unless you are hedging tail risk or speculating on an unforeseen macroeconomic shock, leave the lottery tickets on the shelf.
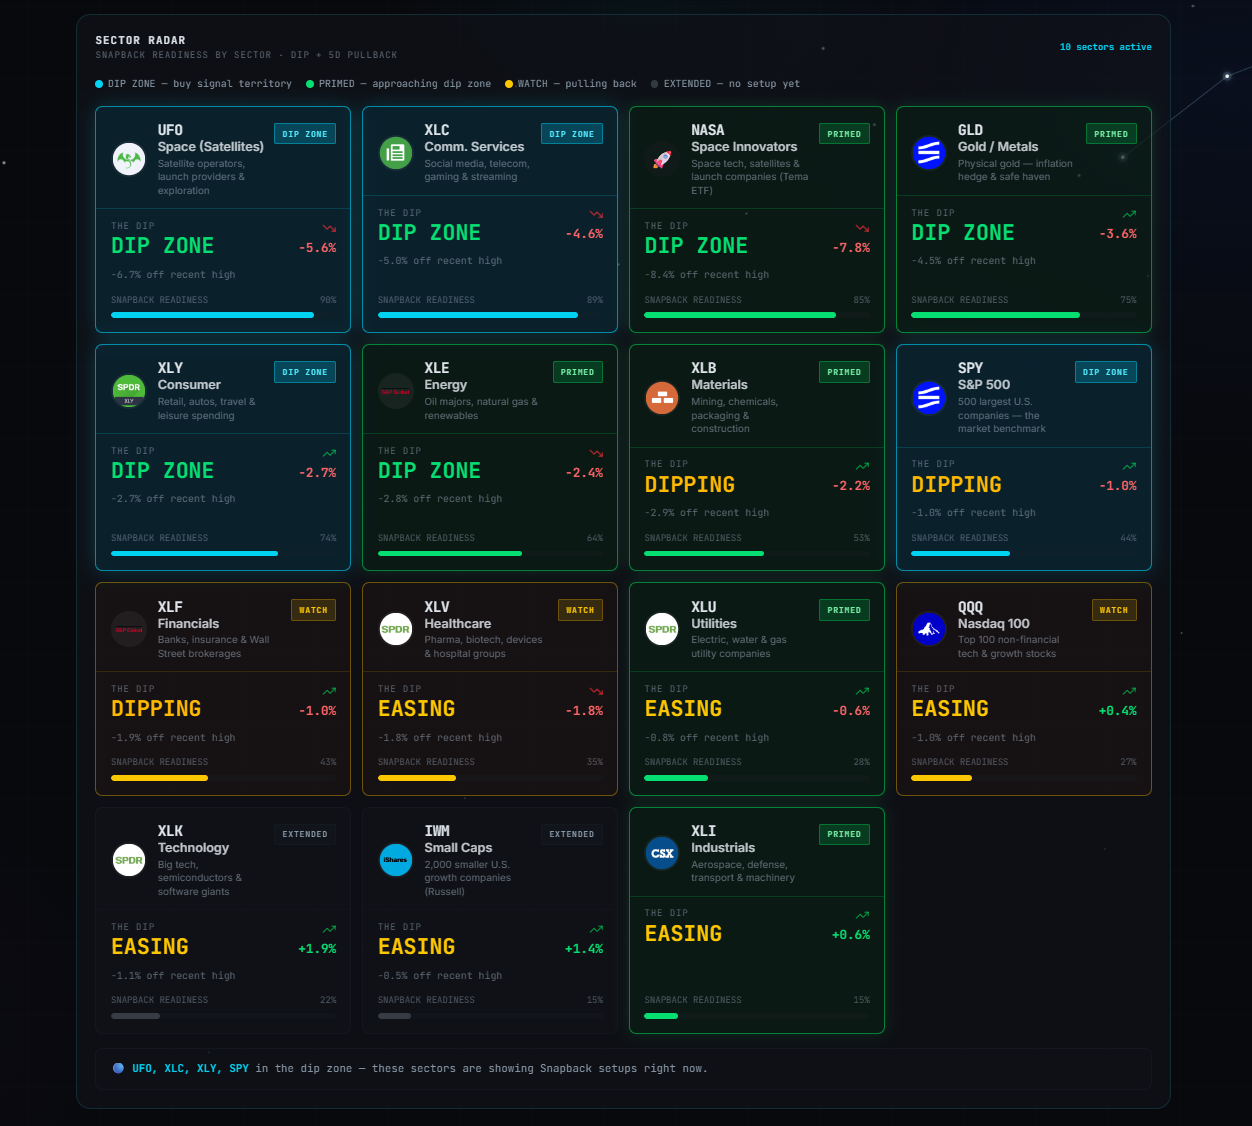
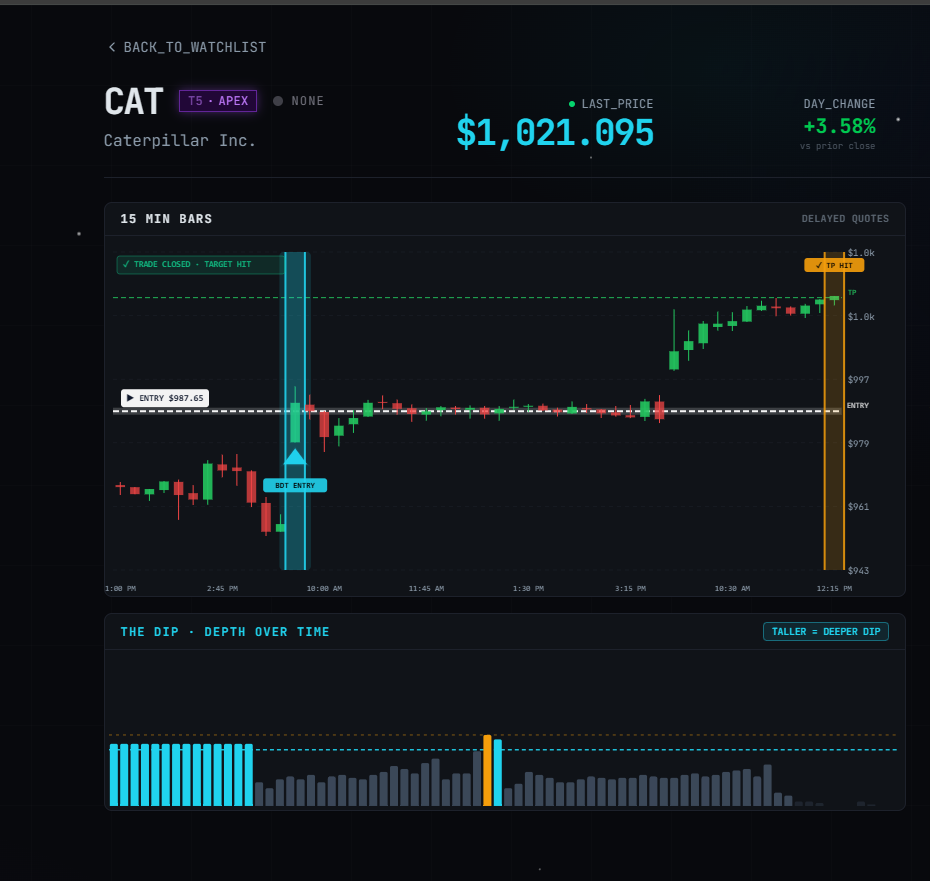
🎯 Want Setups Like These? The Big Dipper Does the Scanning For You.
Every morning the Big Dipper delivers curated DIP ZONE trade ideas — stocks already at high-probability entry levels, with targets pre-set. No guessing, no scanning. Just setups.
From Find Better Trades
Learn The Spread System From The Ground Up
Build, manage, and exit low-risk debit spreads for consistent income — full video course.

OTM Options Trading FAQ
Q: Why do my out-of-the-money calls lose money when the stock goes up?
A: Your contracts lose value because the rate of daily theta decay and the collapse in implied volatility outpace the small gains generated by the low Delta of an out-of-the-money strike.
Q: What Delta should I target for directional swing trades?
A: Target a Delta between 0.70 and 0.85 on contracts with 45 to 60 days until expiration to minimize time decay and mimic stock replacement behavior.
Q: Are weekly out-of-the-money options ever profitable over the long run?
A: No, consistently buying naked weekly out-of-the-money options produces a deeply negative expected value that eventually depletes trading capital due to terminal theta decay.
📈 Want More? Join Our Free Trading Community
- Trading Strategy Guides Telegram — daily strategy tips and market insights
- Find Better Trades Telegram — free trade signals delivered to your phone
- Find Better Trades on YouTube — live trade breakdowns and tutorials